Updated on November 13, 2026
📊 Outsourcing to China still works in 2026 for products that need speed, supplier depth and automated plants, and it has stopped working as a cheap-labor play, especially for goods sold in the US. In 2012 we said on this page that China would not follow India and become a global outsourcing hub.
Our reason was talent: not enough graduates ready for service exports, weak English, few middle managers. Fourteen years later, the picture is stranger than anyone expected.
China shipped USD 3.77 trillion of goods in 2025, a record, with a trade surplus of USD 1.19 trillion. In the same year US imports from China fell 28% in real terms, and buyers in Ohio and Hamburg kept asking their suppliers in Dongguan whether they had a plant in Vietnam yet.
Whether outsourcing to China works for you depends on what you make, and on where you sell it.

1. Why is outsourcing not working in China the way it used to?
The old model was simple. A foreign brand sent a design to China and bought the lowest unit price. Three things broke it. Labor now costs about twice as much as in Vietnam. Tariffs and export controls add a political cost that can change between the purchase order and the delivery.
And the Chinese suppliers worth working with are often more advanced than their clients, which shifts the balance of power in the relationship.
China’s production base itself is intact. Its factories still offer speed, dozens of component suppliers within a two-hour drive, and engineering capacity that no single alternative country can match. Most of the companies we speak with are staying in China and splitting the supply chain instead: China for some products and markets, another country for the rest.
2. Outsourcing and sourcing in China: the figures in 2026
| Indicator | Latest figure | Source |
| China’s goods exports | USD 3.77 trillion in 2025, up 5.5%; trade surplus USD 1.19 trillion | General Administration of Customs via The Paper, Jan 2026 |
| China’s exports, first nine months of 2026 | RMB 23.2 trillion, up 16.4% year on year | Customs data via Xinhua, Oct 2026 |
| Average manufacturing wage, urban non-private units | RMB 113,594 per year in 2025, up 5.2% | National Bureau of Statistics, May 2026 |
| Average manufacturing wage, urban private units | RMB 76,055 per year in 2025, up 6.4% | National Bureau of Statistics, May 2026 |
| Manufacturing worker income in Vietnam | USD 364 per month in Q1 2025 | Vietnam National Statistics Office via VIR |
| Foreign direct investment actually used in China | RMB 747.7 billion in 2025, down 9.5% | Ministry of Commerce via China Daily, Jan 2026 |
| China’s outward direct investment | USD 213.6 billion in 2025, up 11.1% | MOFCOM, NBS and SAFE bulletin via Xinhua, Sept 2026 |
| China’s share of US goods imports | About 9% at end-2025, against 22% in 2018 | Peterson Institute for International Economics, March 2026 |
| Average US tariff on Chinese goods | About 36.5% as of July 2026 | Congressional Research Service, Aug 2026 |
| Offshore services outsourcing executed by Chinese firms | RMB 1.17 trillion in 2025, 42.8% of it knowledge process outsourcing | Xinhua, June 2026 |
| Industrial robots installed in China | 295,000 units in 2024, 54% of global installations | International Federation of Robotics, Sept 2025 |
If you do the math with these numbers, three things come out (our calculations). China lost about three fifths of its share of US goods imports in seven years. Its total exports kept rising anyway.
A Chinese factory worker in a private company earns around USD 880 a month, if you convert at about RMB 7.2 to the dollar. That is roughly 2.4 times a Vietnamese manufacturing worker. And in 2024 China installed more industrial robots than the rest of the world together.
So the export machine is bigger than ever, but the US market is slipping away from it. And Chinese companies now invest more abroad than foreign companies invest in China.
China’s export machine is bigger than ever, yet its share of US goods imports fell from 22% in 2018 to about 9% in 2025.
What we wrote in 2012, and what still holds
The first version of this article was about talent, and part of it has aged well. Here is its core argument, lightly edited.
It is highly unlikely that China will follow India to become a global outsourcing hub. One of the main constraints is that few of China’s vast number of university graduates are capable of working successfully in the services export sector, and the fast-growing domestic economy absorbs most of those who could.
The growing number of multinationals in China, as well as ambitious Chinese companies, are facing a shortage of Chinese-born talent, and this may hinder economic progress in the longer term.
China’s pool of potential talent is nevertheless enormous. In 2003, there were around 10 million young professional graduates with up to seven years’ work experience, and an additional 97 million people that would qualify for support-staff positions (figures from a 2005 McKinsey Global Institute study on China’s looming talent shortage).
The problem is that very few had the necessary skills for service occupations.
The educational system tended to be biased toward theory rather than practical experience, which is vital in industries such as engineering. Chinese students also had a low level of English compared to students in India, and effective managers were in short supply.
Multinational companies did train and promote managers from entry-level positions, but the process was time-consuming and costly. With levels of FDI so high, multinationals often resorted to headhunting between themselves. A greater source of middle-management talent was the large number of ethnic Chinese employed as managers by companies in Hong Kong, Singapore and Taiwan.
These people could be recruited to mainland China, but often required better packages, including wages and benefits above what the locals received, though less than the full expatriate package. Companies needed graduates to improve their market research and product development, understand consumer tastes, build after-sales service and raise local financial and accounting standards.
| What we wrote in 2012 | Status in 2026 |
| China will not become a global outsourcing hub like India | Half right: no voice and back-office hub, but a RMB 1.17 trillion offshore services sector built on engineering and R&D |
| Few graduates can work in service exports | Turned around: 12.7 million graduates expected in 2026 and 18.9% youth unemployment in August 2026 |
| English is weak compared with India | Still true: China ranks 86th in the EF English Proficiency Index 2025, India 74th |
| Middle managers are scarce and poached between multinationals | Still true at the top: experienced plant and quality managers remain hard to hire and keep |
| China leads in basic labor-intensive manufacturing | No longer: labor-heavy categories are the first to leave; China competes on automation and supplier depth |
The English gap is the part that held. In the EF English Proficiency Index 2025, China ranks 86th out of 123 countries and regions, behind India (74th) and Vietnam (64th), and far behind the Philippines (28th). Voice-based call center work for Western clients never moved to China at scale, and it is unlikely to now.
Almost everything we said about scale aged badly. The graduate shortage of 2005 has become a surplus at entry level.
3. Services outsourcing: China went its own way
Services outsourcing in China grew without the call-center image that India built in the 2000s. According to Xinhua (June 2026), Chinese companies executed RMB 1.17 trillion (11,688.8亿元) of offshore services outsourcing in 2025. Knowledge process outsourcing (R&D, design, engineering analysis, data work) made up 42.8% of it.
In twenty years the sector went from about 500 companies to more than 90,000, and from fewer than 60,000 employees to 17.66 million.
China never won the help desk. What it won sits close to hardware: embedded software for cars, chip design support, testing labs, industrial software, data labeling for AI models. When a European machinery maker hands its control software to a team in Suzhou, it is paying to sit next to the factories that will run that software.
The talent problem we described in 2012 has flipped as well. The Ministry of Education expected 12.7 million college graduates in 2026 (1270万), 480,000 more than the year before. The National Bureau of Statistics put the urban unemployment rate for 16 to 24 year-olds not in school at 18.9% in August 2026, up from 17.9% in July.
In 2005 multinationals fought over a small pool of graduates; in 2026 a hiring manager in Chengdu can get several hundred CVs for one junior analyst role.
The shortage has moved up the ladder, to experienced engineers who can lead teams and to managers who can run a site under a foreign group’s reporting rules. Our article on youth unemployment in China looks at the causes.
4. Manufacturing outsourcing: cheap labor is gone, the factories are still there
For most companies, “outsourcing to China” means contract manufacturing and sourcing. This is where the cost equation has moved most since 2012.
Labor costs in China and Vietnam
In 2025 the average manufacturing worker in urban non-private units earned RMB 113,594 a year, up 5.2%. In private companies, where most export factories sit, the figure was RMB 76,055, up 6.4%, according to the same NBS release. In both categories manufacturing pay rose faster than the national average.
Vietnam’s statistics office put average monthly income for manufacturing workers at USD 364 in the first quarter of 2025. Against our estimate of about USD 880 a month for a Chinese private-sector factory worker, that is a gap of roughly 2.4 to 1.
The two statistics are built differently (wages in one case, income in the other, with different scopes), so read the ratio as an order of magnitude.
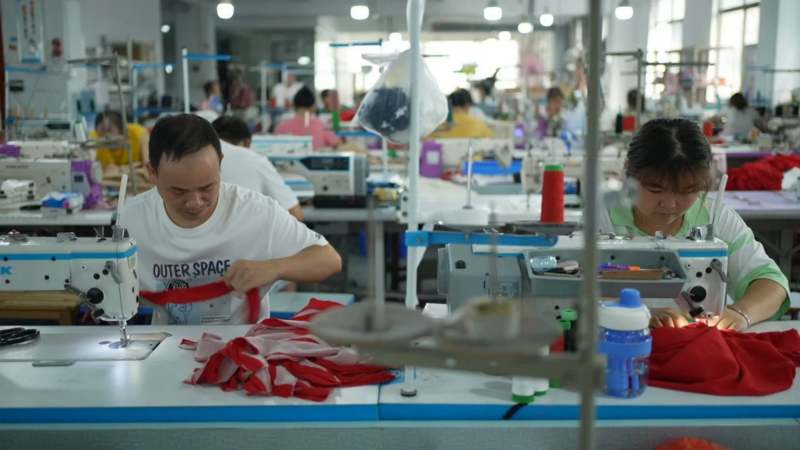
On a garment, shoe or furniture order, where labor is a large share of the unit cost, that gap decides the matter. On an electric motor, a battery pack or a circuit board assembly it counts for much less, because labor weighs less in the cost and supplier depth weighs more.
Automation is how Chinese factories answered rising wages
China installed 295,000 industrial robots in 2024, 54% of all robots installed worldwide that year, according to the International Federation of Robotics. For the first time Chinese robot makers sold more units at home than foreign suppliers did, with a 57% domestic share, and China’s operational stock passed 2 million units.

Did automation save China’s cost advantage? Partly. It protects capital-intensive and precision categories, where a Chinese plant can now beat a newer plant in Southeast Asia on defect rates and lead time. It does far less for hand-sewn products or assembly lines that change every season, and those are the categories that left first.
Foreign managers in China report the same mix. In the European Chamber’s 2026 Business Confidence Survey, 75% of respondents said their China-based production is more efficient than their operations elsewhere, while 68% said doing business in China had become harder over the past year.
Most sourcing decisions we see in 2026 come down to that tension between efficient plants and a harder environment.
5. China+1 in practice: who is moving what, and where
China+1 means keeping production in China while adding at least one other country, usually in Southeast Asia, South Asia or Mexico, to serve some markets or spread risk. In 2018 it was a slide in a board presentation. By 2025 it showed up in customs data.
The US import data
The Peterson Institute found that China’s share of US goods imports fell to about 9% by the end of 2025, from 22% in 2018. Imports from China fell 28% in real terms in 2025, while imports from the rest of the world rose about 9%.
Speed varied by product: US imports of laptops, monitors and game consoles from China fell about 70% in 2025, smartphones about 40%, and furniture and footwear had already moved during the first trade war.
Since 2017 Taiwan has gained 4.1 percentage points of US import share, Vietnam 3.7 points and Mexico 2.3 points.
Vietnam and Southeast Asia
Vietnam received USD 27.6 billion of disbursed FDI in 2025, up 9% and the highest in five years, with 82.8% going to manufacturing and processing. Who invested is the interesting part. Mainland China was the second-largest source of newly registered capital (USD 3.64 billion) and Hong Kong the third (USD 1.73 billion).
Together that is USD 5.37 billion, about 31% of the total and more than Singapore’s USD 4.84 billion, the largest single source (our calculation from the same data).
A good part of China+1 capacity is built and run by Chinese companies, as we described in our article on what brings Chinese companies to ASEAN.
What stays in China
Some supply chains will not move soon. China produced over 90% of the world’s neodymium magnets in 2024, according to the same Peterson Institute analysis. When Beijing restricted rare earth magnet exports in April 2025, car plants outside China had to stop lines.
Batteries, solar components, many electronic components and much of the tooling used in factories in Vietnam or Mexico still come from China. Our article on rare earths in China covers this dependency.
Chinese customs data for 2026 points the same way. In the first nine months of the year exports rose 16.4% in yuan terms, and equipment manufacturing accounted for nearly 90% of the increase.
Exports of electronic components rose 70%, integrated circuits 99.1% and electric vehicles 72.3%. Some of those components end up in factories in Vietnam, Mexico or Hungary, which Western importers then count as “not China”.
6. Tariffs and controls in 2026: the cost no sourcing spreadsheet captured in 2012
In 2012 the risks of outsourcing to China were mostly operational: quality, intellectual property, a supplier that disappeared after the deposit. In 2026 the largest risk is policy, and it moves fast.
The Congressional Research Service summarized the sequence. The US Supreme Court ruled that the emergency-powers (IEEPA) tariffs were unlawful, and they were lifted in February 2026. A temporary tariff under Section 122 followed and expired, and in July 2026 a new 12.5% Section 301 tariff was imposed on Chinese goods.
As of July 2026 the average US tariff on Chinese goods was about 36.5%, and China’s average tariff on US goods about 31%.
For a buyer the volatility hurts more than the rate. Take a product bought with a 7% margin: a tariff change between purchase order and delivery can wipe that out. So some companies now pay for a second source they barely use. It works like insurance, and like insurance it looks expensive until the year it pays out.
Capital flows tell the same story. Foreign direct investment actually used in China fell 9.5% in 2025 to RMB 747.7 billion, even though the number of newly established foreign-invested companies rose 19.1% to 70,392, according to MOFCOM.
More entries, each smaller. Chinese outward direct investment, meanwhile, reached USD 213.6 billion in 2025, up 11.1%, with 58,000 overseas enterprises in 189 countries and regions.
7. Common misconceptions about outsourcing to China
“Everyone is leaving China”
The data does not support it. Exports grew in 2025 and again in 2026, and 75% of European Chamber respondents rate their China plants as more efficient than their other sites. What is leaving is a slice of production for the US market, mainly in labor-heavy and tariff-exposed categories.
“China is still the low-cost option”
On labor, no: a Chinese private-sector factory worker costs roughly twice to two and a half times a Vietnamese one. On total cost China often still wins, once you count lead time, supplier density, defect rates and the cost of shipping Chinese components to a plant elsewhere. That sum has to be done product by product.
“Moving to Vietnam or Mexico removes China risk”
Often it only moves the risk upstream. If the moulds, the electronic parts and the factory owner are Chinese, the supply chain is still exposed to Chinese export controls, and more and more to rules-of-origin checks in the US and Europe.
“China cannot do services outsourcing”
China lost the English-language voice market. It built a RMB 1.17 trillion offshore services industry anyway, centered on engineering, software and R&D work done near its factories.
Daxue Take
I wrote on LinkedIn on July 6, 2026 about light-asset and heavy-asset models in China, with cases from Gap and Baozun to Volkswagen and XPeng, Estée Lauder, L’Oréal and BASF. My point: “Few treat it as the structural choice it actually is.” Outsourcing is the light-asset end of that choice.
In our experience it rarely gets the same attention as building a plant, and it should.
The first question we now ask is simple: this product is for which market? In our projects we see a split more and more often. China-made products go to China, Asia, the Middle East and Europe, and a second source serves the US.
A sourcing map drawn by product family hides this. Draw it by destination market and tariff exposure, and the decision becomes clearer.
Draw your sourcing map by destination market and tariff exposure, not by product family. Then the China decision becomes much clearer.
Chinese suppliers have also moved up the value chain, often faster than their foreign clients. In small appliances, EV components and consumer electronics, the supplier frequently has more R&D staff than the buyer’s own product team. If you still pick them on price, as if they were all the same, you lose what they could bring as development partners.
Clear IP rules on both sides make that possible. Our home appliance market article shows how some of these suppliers now compete with their former clients’ brands, and our guide to Chinese OEM companies looks at the contract manufacturers themselves.
Then check who owns the plant abroad. Mainland and Hong Kong investors together put more new registered capital into Vietnam in 2025 than Singapore did. So “China+1” often means China plus a Chinese-owned factory somewhere else.
Who owns it, where its components come from and how rules of origin will treat the finished product matter as much as its address.
On people, our 2012 advice is out of date. With 12.7 million graduates in 2026, hiring juniors is easy. Experienced plant managers, quality leads and engineers who can work inside a foreign group’s systems are still hard to find and to keep. We would spend on keeping a few of those people, not on headcount.
So what would we do? We would put policy risk into the unit cost. Our hypothesis is that tariffs between the US and China will stay volatile through 2027, whatever the headline rate. Build two or three scenarios, let’s say today’s tariff, plus 15 points and minus 10 points, into every sourcing decision.
Keep a qualified second supplier for any product where the US is a large share of sales. In practice we start with a cost-to-serve model per product and destination market, test it against those scenarios, and only then decide what stays in China, what moves and what gets a second source.
Do it once a year, not once a crisis. Our business and marketing strategy team supports these decisions with supplier interviews, field visits and market data, and our guide on how to find suppliers in China covers the first steps.
FAQ about outsourcing in China
Is it still worth outsourcing manufacturing to China in 2026?
For many products, yes. China has the deepest supplier base, fast lead times and highly automated plants, and its exports grew 16.4% in yuan terms in the first nine months of 2026. For labor-heavy products sold mainly in the US, tariffs of about 36.5% on average and labor costs above Vietnam’s make a second country worth studying.
How much does a factory worker cost in China compared with Vietnam?
In 2025 the NBS average wage for manufacturing in private urban units was RMB 76,055 a year, around USD 880 a month by our conversion. Vietnamese manufacturing workers earned about USD 364 a month in Q1 2025. The ratio is roughly 2.4 to 1, with differences in how each country measures pay.
What is China+1?
China+1 is a sourcing approach where a company keeps production in China and adds at least one other country, such as Vietnam, India, Thailand or Mexico. The aim is to reduce exposure to tariffs, export controls and disruptions while staying in China.
Why did China not become an outsourcing hub like India?
China never built India’s English-speaking voice and back-office industry; it ranked 86th in the EF English Proficiency Index 2025. It did build a large offshore services sector focused on IT, engineering and R&D, worth RMB 1.17 trillion in 2025, with 42.8% in knowledge process outsourcing.
Are foreign companies leaving China?
Most are not. The European Chamber’s 2026 survey found that 75% of respondents consider their China production more efficient than elsewhere. Foreign direct investment used in China fell 9.5% in 2025, but the number of new foreign-invested companies rose 19.1%, which points to smaller, more targeted investments.
In conclusion
In conclusion, outsourcing is not working in China the way it did in 2012, when the business case rested on cheap labor and the main risk was a bad supplier. China is now where you buy speed, engineering depth and automated capacity, at a price that includes policy risk.
Brands that compare factory quotes line by line will keep being surprised; those that model total cost per destination market and keep a second source ready will get the most out of their Chinese suppliers.
I founded Daxue Consulting in Beijing in 2012, and we have since delivered more than 800 projects. Our mission is to guide businesses to holistic growth in China, through consumer research, market analysis, tech-enabled data collection and strategy consulting, with teams in Shanghai, Beijing and Hong Kong.
Two of our values shaped this update: intellectual humility, which meant checking a 2012 prediction that the data only partly supports today, and “embrace change enthusiastically”, because the way companies source from China has changed more in five years than in the fifteen before.
To discuss what these shifts mean for your supply chain or your market entry, explore our China market research services or contact our team.
About the author
Matthieu David-Experton is the founder and CEO of Daxue Consulting. He arrived in China in 2009, founded Daxue in Beijing in 2012 and lives in Shanghai. Since then his team has delivered more than 800 projects for international brands, from consumer understanding to market entry and route-to-market, and Daxue has written about outsourcing in China since 2012.
He studied at ESSEC and at Peking University’s Guanghua School of Management, hosts the China Paradigm podcast and writes regularly on retail and channels in China on LinkedIn.