The ecosystem at a glance
Social media platforms in China sit at the center of daily life, folding messaging, short video, search, payment, and shopping into a single screen. One app here covers what messaging, video, and payment apps handle separately in most other markets, which is why screen time concentrates in a handful of names.
- Mobile internet users at 1.28 billion in December 2025
- The five largest content platforms count a combined 1.15 billion monthly active users (MAU) once overlaps are removed
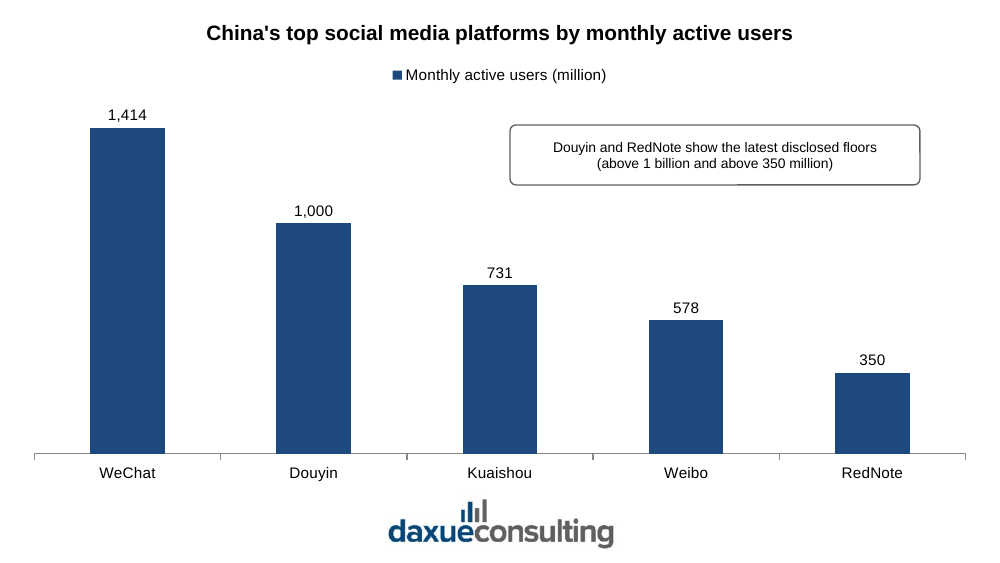
- WeChat (微信) leads the ranking at 1.41 billion monthly active accounts, a global figure that counts Weixin and the overseas WeChat together, Douyin (抖音), TikTok’s Chinese counterpart, sits above 1 billion, and Kuaishou (快手), Weibo (微博), and RedNote (Xiaohongshu, 小红书) fill out the top tier
- The average user spends 7.96 hours a day on mobile apps, up 6.0% in a year, and time on the big content platforms grew 5.4% while user counts barely moved
The 1.15 billion figure represents unique users after removing overlaps. For example, a single person who uses both WeChat and Douyin is counted once. The individual platform MAU numbers are higher because they count each user per platform. WeChat’s 1.41 billion is also the only global number in this list. It counts accounts rather than people, and one person can hold more than one, which is why it can top the count of internet users in China.
Social media platforms in China are now building storefronts inside their apps, selling targeted advertising to brands. For brands, the question has shifted from where Chinese consumers are to which platform earns their hours and their orders.
A deep dive into the Big Five
Five social media platforms in China make up the top tier, and four of them carry most brand budgets. Brands use WeChat for memberships, repeat purchases, and private traffic. Its 1.41 billion accounts hold chat, payments, and mini programs in one place, and its Channels feed pushes short video and livestream selling into what users treat as a private messaging space. Tencent moves carefully there, since heavy ads would spoil the reason people open the app.
Most active short video platforms: Douyin and Kuaishou
Douyin and Kuaishou split the short-video audience. For brands that want the widest reach, Douyin is the obvious pick, with more than 1 billion MAU. It already carries a heavy ad load, so each extra ad slot trades against the watch time it depends on. For brands targeting price-sensitive or tier-3 city consumers, Kuaishou is the essential platform, with 731 million MAU and 56.3% of them in tier-3 cities and below. Its task is raising revenue per user from a base that spends less than big-city audiences. Both apps now reach far past the young crowd, with users aged 51 and above at about 22% on each.
For brands, RedNote is where the purchase decision takes shape. Notes and reviews double as product research, and of its 350 million MAU, 170 million come each month with something to buy in mind, which is why the platform guards its community tone against ad fatigue. Weibo stays in the top tier by size, with 578 million MAU, and it owns hot topics, generating 60,500 of them in the third quarter of 2025 alone. Its traffic follows news and celebrities rather than shopping, so brands use it for launches and public moments instead of daily sales. The other two serve narrower jobs. Bilibili (哔哩哔哩, B站) holds the youngest crowd with 66.5% of users under 30, and Zhihu (知乎) covers long-form Q&A. Use them when a campaign targets their specific audiences.
Platform roles, audiences, and strategic tensions
| Platform | Main use | Who is on it | Strategic tension |
| WeChat (incl. Channels) | Messaging, payments, mini programs, private traffic | Everyone; Channels skews older with high spending | Monetizing Channels without ruining the private messaging experience |
| Douyin | Short video, livestream shopping, mass-reach ads | Broad across ages and city tiers; 51+ at 22.2% | Adding ad load without cutting the watch time it sells |
| Kuaishou | Short video with strong creator-fan ties | 56.3% in tier-3 cities and below | Lifting revenue per user on a lower-spending base |
| RedNote | Product research, reviews, lifestyle search | Young and urban; 54.2% under 30, 37.2% in tier-1 and new tier-1 cities | Commercializing without breaking community trust |
| Hot topics and public discussion | Broad public; 578 million MAU | Turning hot topics into steady ad revenue |
Platform choice cheat sheet
- Want mass brand awareness? → Douyin / Kuaishou
- Want to build a loyal customer community? → WeChat
- Want to drive product research and consideration? → RedNote
- Want to ride hot topics and public moments? → Weibo
- Want a niche audience (young video fans, Q&A)? → Bilibili / Zhihu
The engine of commerce
Attention on social media platforms in China converts into sales without leaving the app. Social commerce has moved from side business to main engine. Douyin’s e-commerce GMV grew more than 30% over the first ten months of 2025, putting the full year on course to pass RMB 4 trillion and approaching Pinduoduo’s scale.
WeChat is scaling its own loop. WeChat Store GMV in 2024 reached 1.92 times its 2023 level, a jump that partly reflects a young base, since the store format was only upgraded from video-account shops in August 2024. Brand sellers grew at 4.3 times the platform’s overall pace in 2025, and RedNote keeps transactions inside the community it built. The ad money follows the same path. Tencent’s marketing services revenue rose 21% year on year in the third quarter of 2025, and Kuaishou’s core commercial revenue, which bundles marketing services with e-commerce, grew 19.2% in the same quarter, since what the platforms sell has shifted from impressions to conversion.
For brands the platform choice is now a channel choice. Beauty and lifestyle lines sell through Douyin and RedNote, where discovery turns into checkout in one session. High-ticket standardized products sell through conventional store listings and JD-style fulfillment. Repeat purchases and memberships sit with WeChat, where mini programs and Channels feed a brand’s private traffic.
RedNote and Douyin have become the new search engines
A brand that wants to be found in China can no longer count on search engines such as Baidu (百度). For younger users, and Gen Z in particular, the search habit has moved to social media platforms in China, with RedNote and Douyin serving as the first stop for product and lifestyle queries.
- RedNote now handles more than 800 million searches a day, and 70% of its monthly users run searches on the app
- Douyin counts 5.3 billion daily searches, and 41% of its search users type a query within half a minute of opening the feed
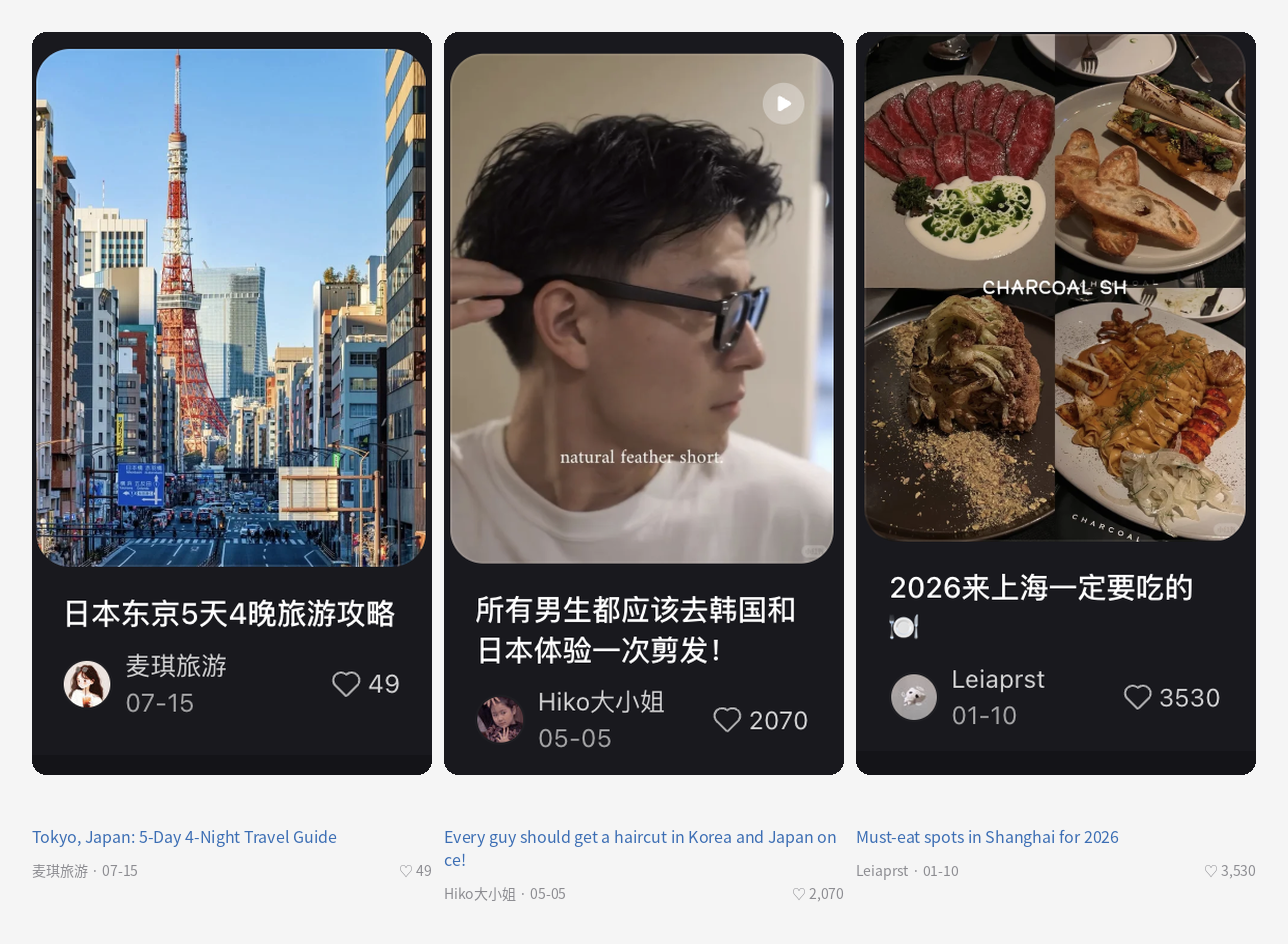
A search for a hair dryer, a hotpot restaurant, or a Tokyo itinerary returns other buyers’ notes and videos in place of ad-heavy web pages, and a well-ranked note keeps pulling readers for years after it goes up. The advertising money has moved with the habit. Brands once put that money into keyword bidding on search engines; it now goes to sponsored posts from creators on RedNote and Douyin, where a promoted note doubles as a search result.
AI runs the content factory around the clock
Human hosts built livestream selling, and they also set its limits. A studio needs anchors, assistants, and operators working in shifts, and even a strong team goes off air at night. Digital hosts removed that ceiling. An AI-generated host streams around the clock at a fraction of the staffing cost, a single operator can run several rooms at once, and iiMedia expects the global digital human livestream commerce market to reach USD 76.8 billion in 2026. AI tools inside Douyin, Weibo, and Kuaishou now count more than 30 million MAU each.
One survey found that only around 20% of consumers say a virtual host directly sways their purchase, and more than 60% still rate a human host’s live interaction as something an AI model cannot match. For brands, the split is practical. Give digital hosts the overnight hours and the standardized products, and keep human hosts for launches and the categories where the buyer needs persuading.
The next users
Brands looking for new growth have two user pools left. At home it is the silver crowd. China counted 161 million internet users aged 60 and above by mid-2025, with penetration in that group at 52%, and users over 50 watch short video for 129 minutes a day, ahead of younger groups. Half of China’s seniors have yet to come online, and the ones online cluster on Channels and Kuaishou. Overseas, RedNote topped the US App Store in January 2025 as TikTok users looked for a new home, giving a Chinese domestic social app a mainstream American audience for the first time, and it has been adding translation and international features since. For brands, these two pools are where the next spending will come from.
Key takeaways on social media platforms in China
- User growth on social media platforms in China has topped out, with the five biggest platforms reaching a combined 1.15 billion people, so the competition has moved to time spent and monetization per user.
- Four platforms carry most brand budgets, and each plays a different game, with WeChat holding infrastructure and private traffic, Douyin selling the widest reach, Kuaishou holding lower-tier cities, and RedNote shaping purchase decisions.
- Social commerce is now the main engine, with Douyin’s GMV heading past RMB 4 trillion in 2025 and WeChat scaling its store loop, so choosing a platform means choosing a sales channel.
- Product search starts on RedNote and Douyin for younger consumers, and seeding notes there now does part of the work that search-engine keywords once did.
- AI hosts stream around the clock at a fraction of human staffing costs, and consumer trust still sits with human hosts. The next user pools are the 60+ crowd at home and RedNote’s new audience overseas.
Author: Ming Yii Lai, with additional research by Zekai Zhang