In 2025, Robam, a leading Chinese kitchen appliance maker, looked untouchable on paper: it sold about 31% of all range hoods and gas cooktops and consistently holds top-three share across major categories. Yet it also recorded its first year-on-year revenue decline since listing in 2010, with net profit down a fifth.
That is the puzzle. How does the dominant firm in a category post its worst-ever year without losing any share? The answer is that demand itself is drying up, as the occasions that drive a household to buy a kitchen appliance are disappearing.
A fifth of the appliance market, falling twice as fast
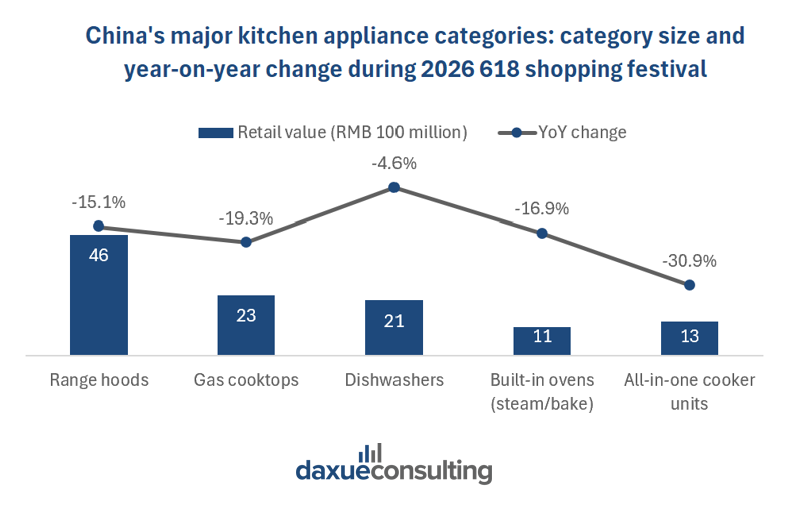
Kitchen and bath appliances, including range hoods, cooktops, sterilizer cabinets, dishwashers, built-in ovens, all-in-one cooker units and water heaters, are tracked by the research agency AVC as one market. In 2025 it was worth about RMB 161bn, down 8.5%, and the decline only steepened: down about 10% in the first quarter of 2026, and 14.4% across the “618” festival that normally props the category up. Against a total appliance market down around 4%, kitchen appliances are falling twice as fast, which points toward a category-specific problem. Therefore, the real question is what makes Chinese households buy kitchen appliances at all.
The subsidy proved price isn’t what ails China’s kitchen appliances market
The clearest evidence comes from the government’s own trade-in subsidy. When launched in September 2024, the subsidy actually worked, with kitchen appliance sales jumping more than 20% YoY over the next four months. Then, in January 2025, the scheme widened to sweep in dishwashers, microwaves, water purifiers and rice cookers, giving more money to more products, but sales went nowhere, slipping 0.6% YoY over the following eight months.
When the 2026 program dropped range hoods and cooktops from the subsidy, the outcome cut against the usual logic that subsidies drive sales. Stripped of state support, those two categories were among the very few still growing in early 2026, even as most of the subsidized market kept falling.
A wider subsidy achieved so little because it merely accelerated existing renovation decisions but couldn’t generate new demand. When the initial pool of renovators dried up, capital lost its leverage. Discounts fail when operational friction is the primary barrier to adoption. Cost was never the binding constraint; the disruption of the project was.
Less new apartments meant less demand
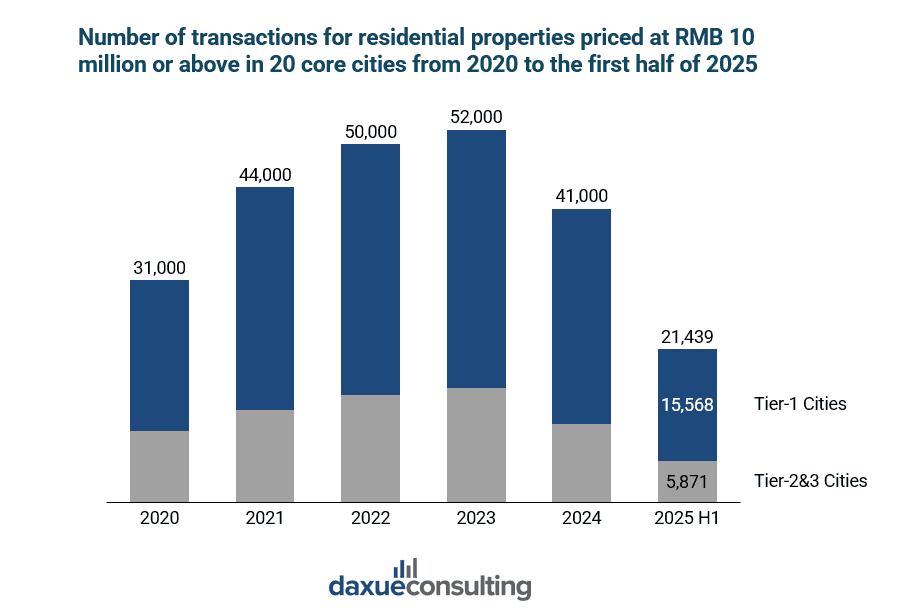
That is why the collapse traces back to construction. In China, many new flats are handed over with the hood and cooktop already installed, so each new apartment is effectively a bulk appliance sale to a developer. Robam built its scale on exactly this, supplying the big property firms from 2009 until this “engineering channel” was more than half its revenue. It is now collapsing: engineering revenue fell about 36% in 2025, tracking a national market for developer-fitted apartments that’s down 22% to roughly 518,000 units.
Nothing shows the dependence on new construction more starkly than the all-in-one cooker unit, a hood, cooktop and steamer or dishwasher fused into one appliance and fitted into cabinetry when the kitchen is built. With more than 60% of its demand coming from new-home fit-outs, this category fell 43% in 2025, the worst of any lines of products. Being installation-heavy, it cannot follow buyers into the retrofit market the way a standalone hood can. Excluding these cookers, the rest of the market fell just 4.8%. What grows now needs no cabinetry, such as countertop dishwashers whose sales more than doubled online, marking a demand shift towards better and easier physical fit.
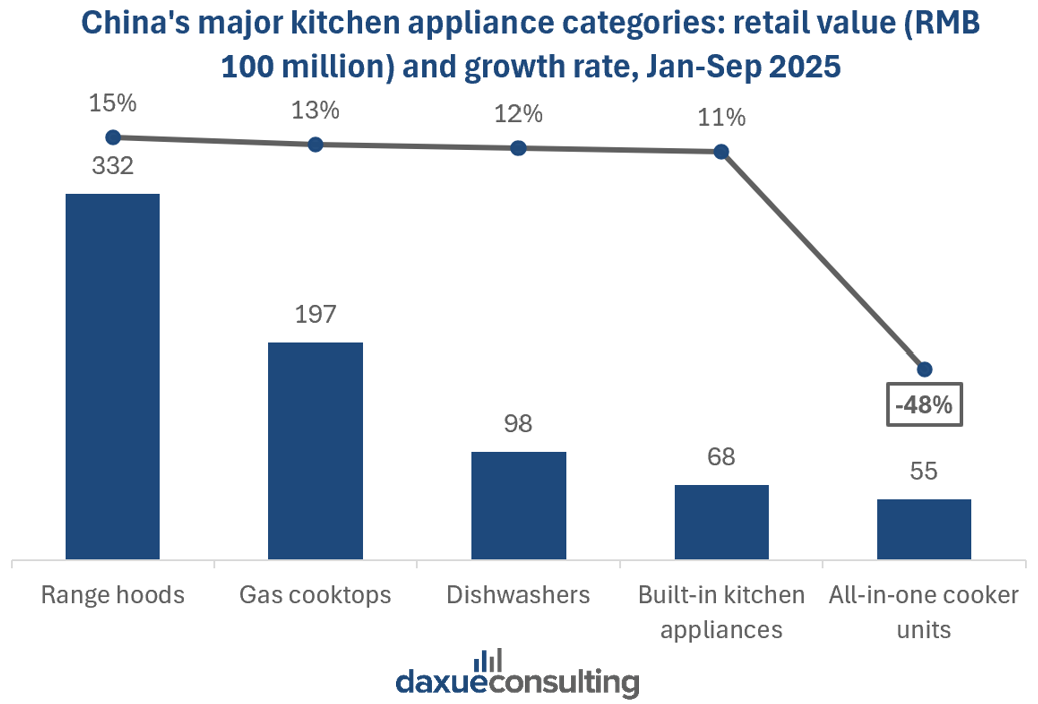
Who is still buying in China’s kitchen appliances market
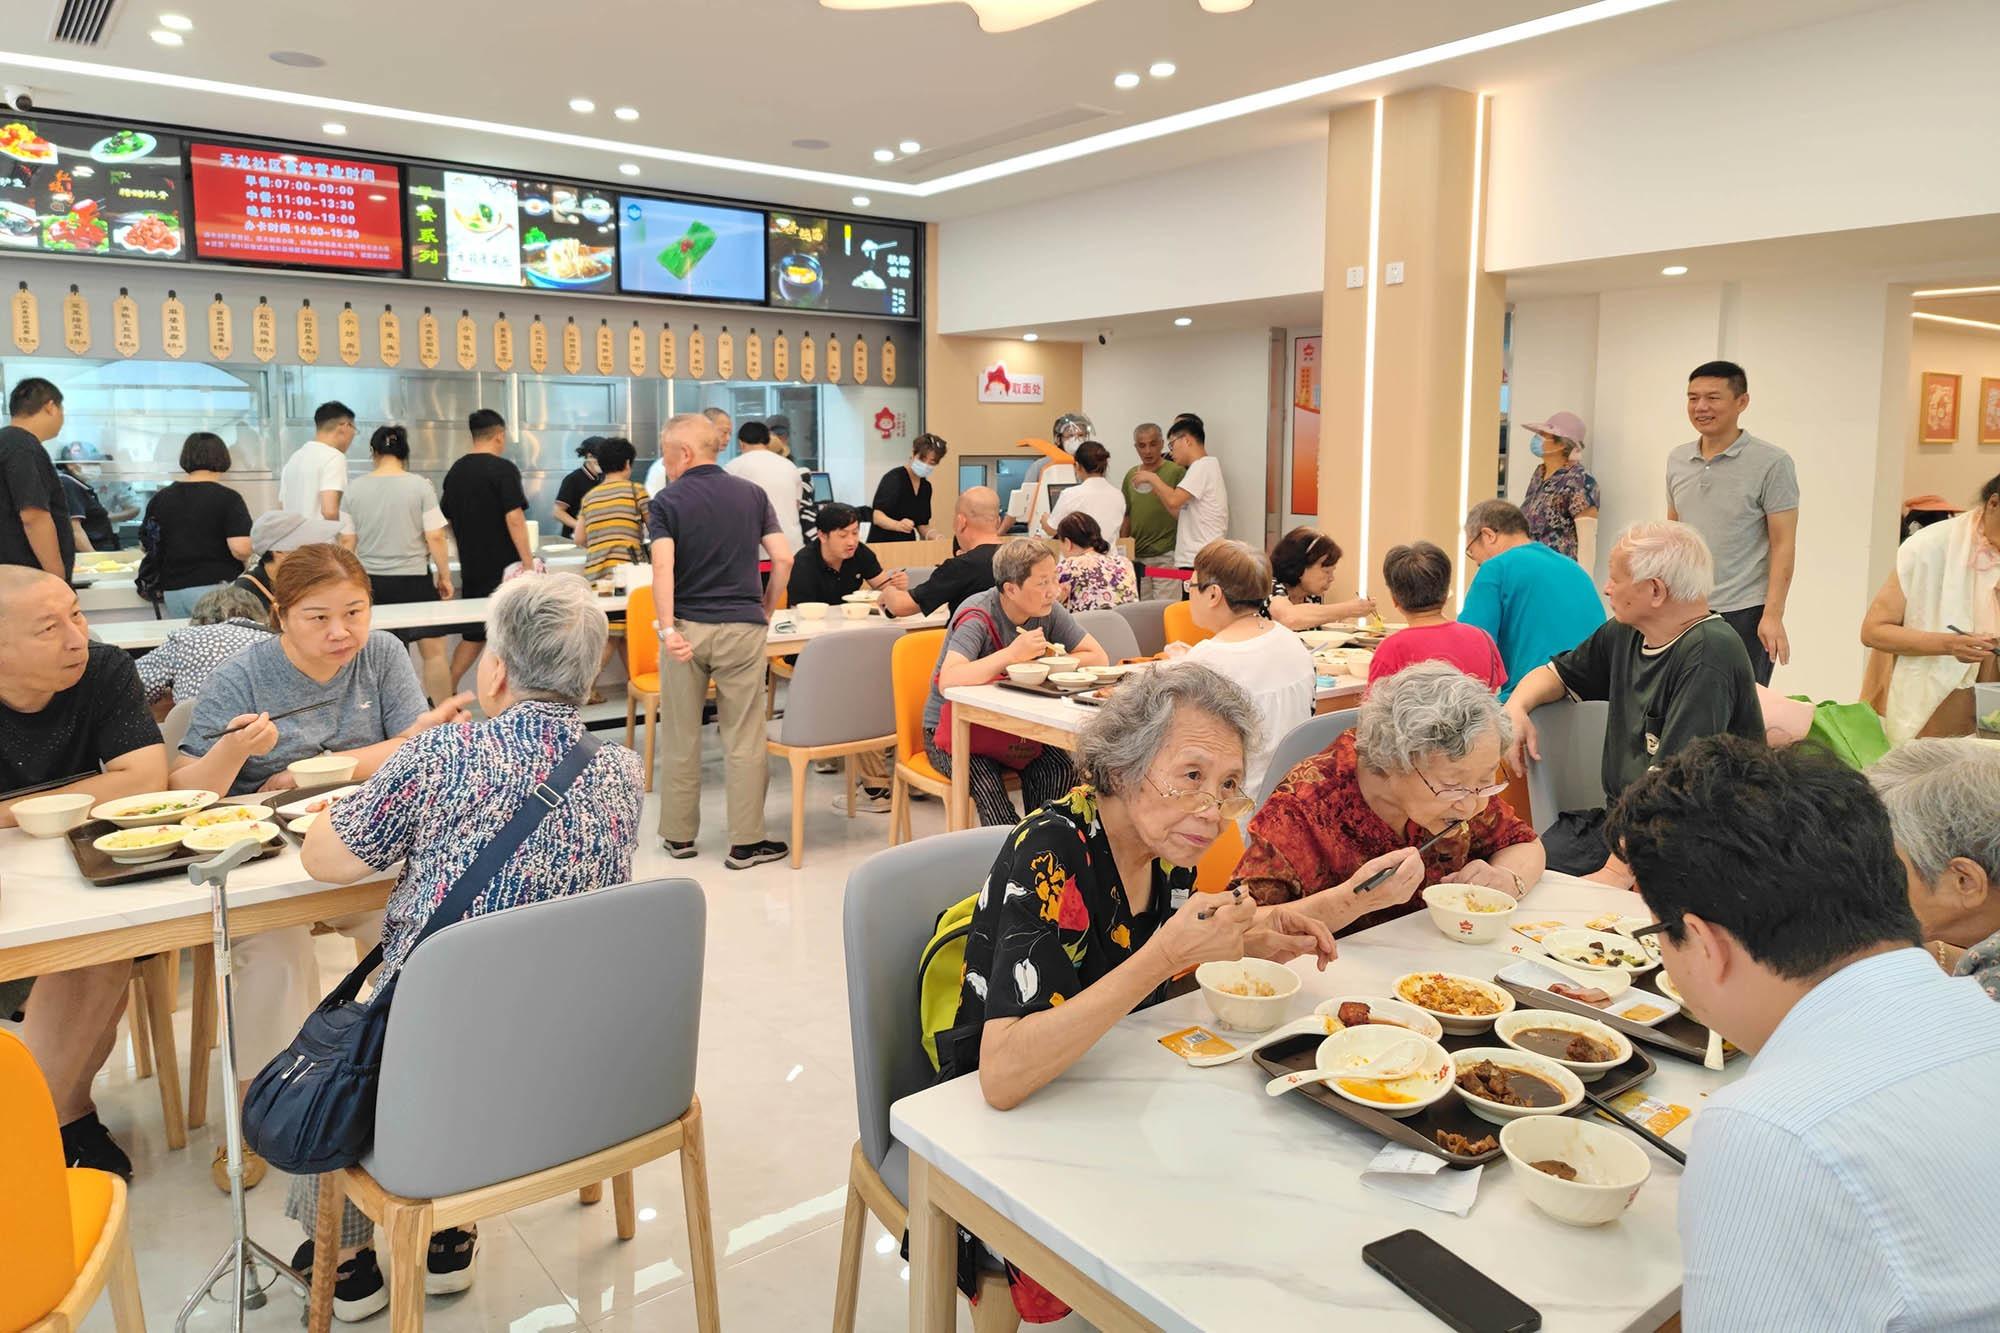
Two cohorts are holding the category up, buying for opposite reasons. Younger households drove the shift in product sales: dishwashers climbed from 6.5% of major kitchen-appliance sales in 2021 to nearly 10% in 2025 as post-80s and post-90s buyers put convenience and space above price. Meanwhile, older households are the buyers policy now favors. The 2026 program added ageing-adaptation products to the subsidy. As a result, kitchen appliances lead every category in adaptation-readiness. For instance, safety features like dry-burn cut-off become increasingly central to what sells, even as the state draws that same cohort partly out of the kitchen through an eleven-ministry push on elderly community canteens.
At the same time, the market beneath both cohorts is defending value rather than volume. In small kitchen appliances, unit sales fell about 15% in the first half of 2026 while average prices rose 12% as cheap unbranded supply cleared out. At the premium end the same instinct shows up as bundling: during the 2026 “618” festival, over 60% of certain high-end lines were sold as part of a matched suite rather than individually, with brands funding those discounts themselves.
The rules now favor the incumbents
With price cuts unable to create demand, the contest has moved to the technical floor. A mandatory standard from March 2026 lifts top-tier gas-cooktop efficiency to 70%, banning direct-vent models and setting an eight-year scrap life. It is those incumbents the rules now protect as they squeeze out low-end producers that cannot meet them.
But protection is not growth, as Robam, the market leader this story began with, shows. Its problem was never capability. Even in its worst year, Robam’s AI kitchen line grew 36% to RMB 2.35bn. The trouble was exposure: its diversification bets, from all-in-one cookers to steam ovens, each fell by roughly half, dragged down with the new-build market they depended on. Dominant share and a leading AI line still could not save it from where its business was pointed. As new standards clear out weaker rivals, the scale and technology that couldn’t shield Robam’s revenue this year may decide who is left once the market contraction finally ends. In China’s kitchen appliances market, holding share and finding growth have become two different things.
What it means for China’s kitchen appliances market
- China’s kitchen appliances market is shrinking twice as fast as appliances overall, down 8.5% in 2025, steepening into 2026.
- Renovation drives the purchase, instead of discounts. A wider subsidy in 2025 lifted nothing as seen in scrapping it in 2026 didn’t stop hoods and cooktops growing.
- Developer-fitted apartments fell 22%; the format tied to them, all-in-one cookers, fell 43%, versus under 5% for everything else.
- Growth now rests in the existing kitchen: retrofit formats like countertop dishwashers. Young generations are trading up on quality and the old consumers prefer conventional ones.
- Scale no longer means growth. Standards and premium suites favor incumbents, yet Robam’s dominant share couldn’t prevent its first revenue decline on record.
Author: Ming Yii Lai, with additional research by Hansel Guo