In 2025, Mao Geping (毛戈平) crossed RMB 5 billion of revenue, up 30%, with RMB 3 billion coming from makeup (21st Century Business Herald). The same year, Yatsen, the parent of Perfect Diary, the brand that defined Chinese makeup in 2019, earned more from skincare than from makeup for the first time, with skincare at 53% of revenue (PEdaily).
These two results say a lot about color cosmetics in China in 2026. Chinese brands are winning, but not the ones, and not in the way, that most people expected five years ago.
Color cosmetics in China : key figures
| Indicator | Figure | Source |
|---|---|---|
| Total cosmetics transaction value, 2025 (all channels) | RMB 1.104 trillion, +2.83% | Industry data via Yicai |
| Share of Chinese (国货) brands in cosmetics, 2025 | 57.37% | Yicai / Consumer Daily |
| Online color cosmetics sales, 2024 (four main platforms) | Above RMB 100 billion, +9.07% | FBeauty via Winshang |
| Color cosmetics on Douyin, 2024 | RMB 47.9 billion, +41.5% | FBeauty via Winshang |
| Makeup brands above RMB 2 billion online, 2024 | 3 (against 23 skincare brands) | FBeauty via Winshang |
| Mao Geping revenue, 2025 | RMB 5.05 billion, +30% | 21st Century Business Herald |
In this article, color cosmetics (彩妆) refers to makeup : foundation, cushion, concealer, lipstick, eye makeup, blush and setting products. Skincare and fragrance are excluded, except when brands sell both.
2019 : the year Chinese makeup went viral
Looking back, 2019 was the turning point. Perfect Diary sold eye shadow palettes through hundreds of KOLs on Xiaohongshu and WeChat groups, Florasis (花西子) built an imperial Chinese aesthetic with carved lipsticks, and both rode Tmall’s Double 11 to the top. We told the story in our Perfect Diary case study. Many fashion and cosmetic brands launched co-branding campaigns in China with unlikely partners, from museums to cartoon characters, and nostalgia marketing in China often resonated with millennials.
At that time, one thing was sure, Chinese consumers were different. They were young, they bought online, and they were happy to try a new brand at RMB 89 rather than pay RMB 350 for a Western lipstick. In general, international brands had a good reputation in China, but the price gap left a lot of room for local challengers.
What happened next : makeup does not scale like skincare
The surprise of the last five years is how hard it is to build a large makeup brand. In 2024, only three color cosmetics brands sold more than RMB 2 billion online in China, and none reached RMB 5 billion. In skincare, 23 brands passed RMB 2 billion and 8 passed RMB 5 billion (FBeauty via Winshang).
Why? Makeup is a fashion product. Consumers love to try, which is great for a launch, and terrible for loyalty. Trends on Douyin last a few weeks. A brand that grows on one viral palette must find the next one quickly, or it disappears. The Douyin top 20 in May 2025 had seven new entrants compared with April, and all three Douyin-native brands of May 2024 had dropped out a year later (Jiemian).
Skincare is different. People stick to a routine, the ticket is higher, and efficacy claims build trust over time. This is why Yatsen moved its center of gravity. Its skincare revenue grew 63.5% in 2025 to RMB 2.28 billion. By deduction, makeup brought around RMB 2 billion, roughly flat on 2024 (our calculation from the reported totals). Perfect Diary is still alive, but the group now presents itself mainly as a skincare company.
Makeup is a fashion product : consumers love to try, which is great for a launch and terrible for loyalty.
Who wins in 2026
1. Premium Chinese makeup : Mao Geping
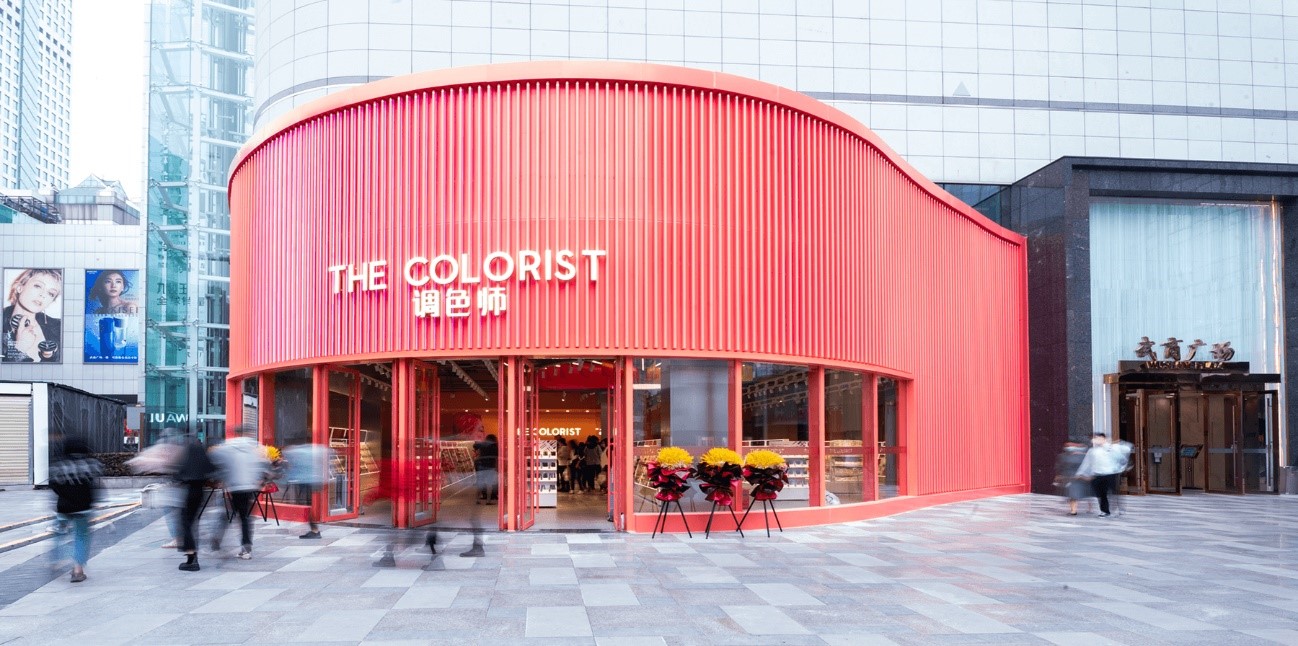
Mao Geping is the opposite of the 2019 model. It sells foundation and cushions at international prices, through 445 counters in 131 cities, mostly in department stores and malls, with makeup artists trained by the founder’s own school. In 2025, its makeup revenue reached RMB 3 billion (+30%), skincare RMB 1.87 billion (+31.1%), and net profit RMB 1.2 billion. For the first time, online sales (50.5%) passed offline.
What it shows is that a Chinese makeup brand can win on artistry and service, not only on price. It also shows that offline counters still matter for complexion products, where people want to test a shade on their own skin. We have a dedicated article on Mao Geping.
2. Mass-market Chinese brands that kept going : Carslan and the base-makeup specialists
Carslan (卡姿兰), a brand born in the early 2000s, passed Florasis in 2024 to become the first Chinese makeup brand online, according to FBeauty. Base makeup (foundation, cushion, concealer) weighed more than RMB 50 billion online, over half of all color cosmetics. The winners in this segment are brands with good formulas for Asian skin, oily skin and long wear, sold at RMB 100 to 200. Eight of the Douyin top 10 makeup products in 2024 were Chinese, with an average price under RMB 150. We profiled several of them in Chinese makeup brands, and the eye category in China’s eye makeup market.
Florasis remains in the top tier, but the brand went through a hard period after a livestream price controversy in 2023, and its growth slowed. Our article on the success of Florasis abroad looks at its international push.
3. International luxury makeup : YSL and the department store brands
International brands have not lost the top of the market. YSL grew close to 20% online in 2024 and stayed the first color cosmetics brand by volume. Among the five beauty brands above RMB 10 billion in China in 2025, three are international (L’Oréal Paris, Lancôme, Estée Lauder), together with Proya and Hanshu (Yicai). In makeup, luxury lipstick and cushion are still a gift and a small treat, the “lipstick effect” that Bain also sees in the strong performance of beauty within luxury.
The middle is where international brands struggle : mass-market makeup lines sold at RMB 100 to 300 now compete with Chinese brands that are often as good, cheaper and faster. We discussed this in Foreign vs Chinese cosmetics brands.
About Daxue Consulting
Daxue Consulting is a market research and strategy consulting firm founded in Beijing in 2012, with offices in Shanghai, Beijing and Hong Kong. We have run more than 800 projects for international brands in China, including many beauty projects : consumer tests, Xiaohongshu and Douyin social listening, brand health tracking and channel strategy.
See our work on the cosmetics and personal care market and cosmetics distribution channels in China.
Channels : Douyin passed Tmall
In 2024, Douyin was the only one of the four main platforms where color cosmetics grew, with RMB 47.9 billion of sales (+41.5%), and it passed Taobao and Tmall in sales and volume. Makeup is visual, it shows well in short videos and livestreams, and a tutorial converts directly into a purchase.
Xiaohongshu remains the place where people research, compare shades and read reviews before buying. Our article on Xiaohongshu (RedNote) explains how it works. Offline, the top 50 beauty brands grew their store sales by 8.89% in 2025 while the market was flat (Yicai), which means counters work for the brands strong enough to run them well.
Chinese consumers are very interested in makeup, yet often lack enough knowledge about formulas and shades for their skin. This is where counters, beauty advisors and content creators do the job that a product page cannot.
New demand : men and fragrance
Young Chinese men are becoming more beauty conscious and confident to take care of their appearance, as we wrote back in 2018. In makeup, this is still a small segment, concealer, brow products, BB cream, but it grows from a low base. See our male beauty market article. Fragrance is the other adjacent category : Mao Geping launched 32 fragrance SKUs in 2025, and we covered the category in China’s fragrance market.
Daxue Overview
- Chinese brands hold 57% of China’s cosmetics market. In makeup, they lead in mass and are entering premium.
- Makeup is harder to scale than skincare. Only 3 makeup brands passed RMB 2 billion online in 2024.
- Douyin is now the first online channel for makeup. Offline counters still matter for base makeup.
- International brands keep the luxury top. The mass middle is under pressure.
Daxue Take
I would tend to think the next phase of Chinese makeup will be less about viral launches and more about craft. Mao Geping shows that consumers will pay international prices for a Chinese brand when the product and the service justify it. That is a different story from “guochao” as a cheaper patriotic alternative.
For international brands, what we observe is that the gap with Chinese competitors is no longer in quality. It is in speed and in understanding of local skin and local taste. A foundation developed for Paris and adapted later rarely beats one developed in Guangzhou for oily skin and humid summers.
Daxue Recommendations
- Brands first need to identify their target consumer needs and understand the competitors, shade by shade and price point by price point.
- Invest in base makeup for Asian skin. It is the largest and most loyal part of color cosmetics.
- Use Douyin for launches and Xiaohongshu for consideration. Do not expect loyalty from one viral product.
- Keep counters where complexion products are tested, and train the advisors.
- Consider skincare and fragrance extensions to build a more stable business.
FAQ
How big is the color cosmetics market in China?
Online makeup sales passed RMB 100 billion in 2024 on the four main platforms. The total cosmetics market reached RMB 1.104 trillion in 2025.
Are Chinese makeup brands winning in China?
Chinese brands held 57.37% of the cosmetics market in 2025. In makeup, Carslan, Florasis and Mao Geping are among the leaders, with YSL first online.
What is the biggest Chinese makeup brand?
Online, Carslan passed Florasis in 2024. In revenue, Mao Geping reached RMB 5.05 billion in 2025, including RMB 3 billion from makeup.
Where do Chinese consumers buy makeup?
Mostly online, and Douyin passed Tmall in 2024. Department store counters remain important for premium and base makeup.
As a conclusion, color cosmetics in China reward craft, speed and skin knowledge more than a big launch budget. The winners of 2019 learned it the hard way. What would your brand need to change to compete with Mao Geping, not only with Perfect Diary?
About the author
Matthieu David is the founder and CEO of Daxue Consulting. He arrived in China in 2009, founded Daxue in Beijing in 2012 and hosts the China Paradigm podcast. He has advised more than 400 companies on their China market strategy.